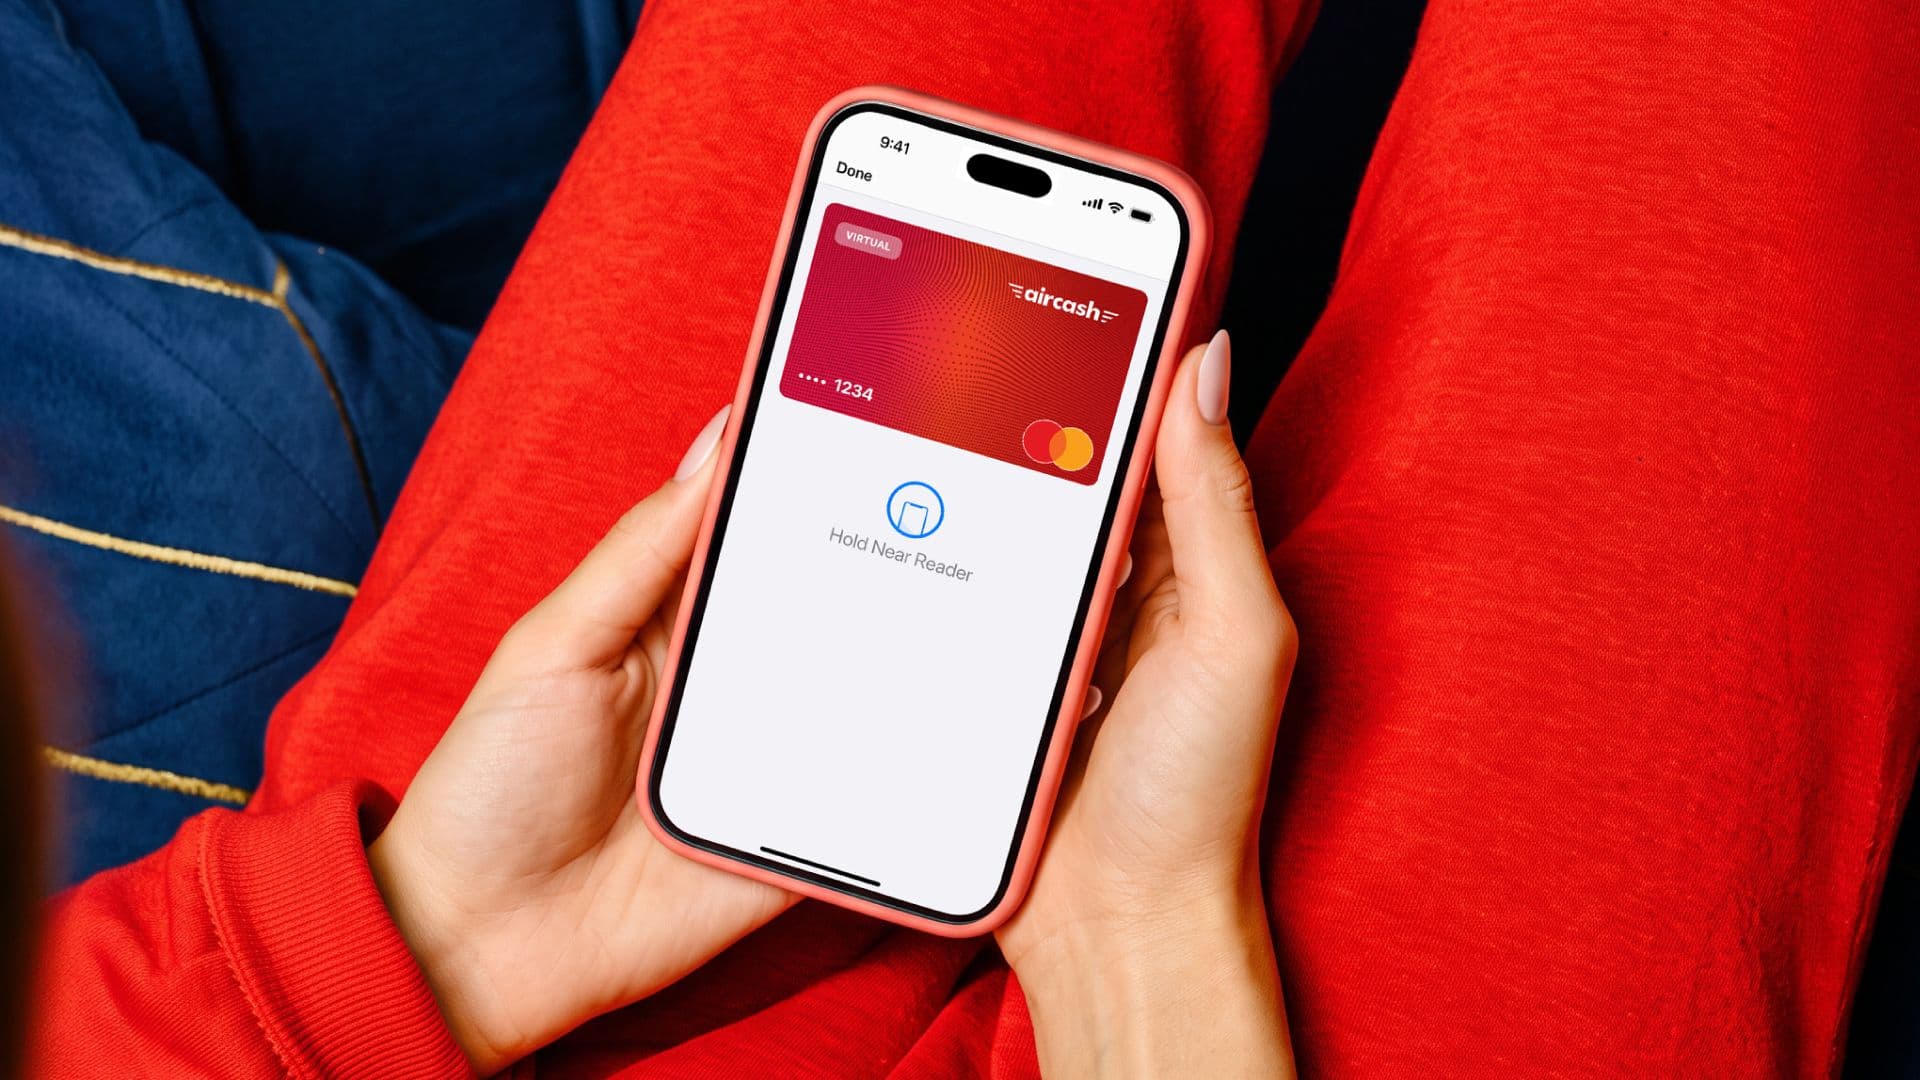
You have a bank card and everything works. So why would you need another one, a virtual card - especially one that exists only on your phone?
Because a virtual card doesn't replace your bank card - it gives you extra control. For online shopping, subscriptions or travel, you use a card that holds only the amount you need, while your main account stays separate.
One card, less exposure. Here's how both work and how they differ.
How does a debit bank card work?
A debit bank card is linked to your current account. That's usually where your salary lands and where your loan repayments or savings come from. When you pay by card, the money is taken directly from that account.
That's convenient in shops and at ATMs. The problem starts when you enter that card's details online. If someone gets hold of them, they could potentially access everything in your account, not just the amount of a single purchase. And if you block the card, you have to wait for a new one and re-enter its details everywhere it was saved.
How does the Aircash Mastercard virtual card work?
The Aircash Mastercard virtual card is a free Mastercard you open in the Aircash app - no branch visit, no paperwork. There's no plastic: you can see the card number, expiry date and security code only in the app.
The card isn't linked to your bank account but to your Aircash wallet. Only the amount you top up yourself is available. If you add 30 euros for a purchase, you can spend exactly 30 euros and not a cent more.
You can pay with it wherever Mastercard is accepted, online and in store. You can add it to Apple Pay or Google Pay and pay with your phone. You can link multiple cards to one Aircash account and manage each one separately, with its own spending limits.
Bank vs. virtual card: a comparison
| Bank card | Aircash Mastercard virtual card |
Linked to | Current account | Aircash wallet |
How much money is exposed | Everything in the account | Only the amount you top up |
How you get it | Application at the bank | Instantly in the app |
Time to issue | Waiting for delivery | Instantly in the app |
Format | Plastic | Only on your phone |
Price | Depends on the bank | Free |
Multiple cards for different purposes | Rarely, with fees | Yes, each with its own limit |
Paying with phone / watch | Depends on the bank | Yes, with Apple Pay and Google Pay |
When should you use a bank card, and when a virtual one?
You'll keep using your bank card for what it was made for: big purchases, spending from your salary and everyday household expenses.
A virtual card is the better choice when:
you're shopping online and don't want to risk your main card's details
you're paying for subscriptions (streaming, apps, free trials) and want to see clearly how much they cost you
you're travelling and want to keep your travel budget separate from the rest of your money
you want to control your spending - for example, with a separate card for online shopping with a monthly limit
You don't have to choose one or the other. Your bank card remains your main account, while the virtual card becomes an extra shield between your money and the internet.
Open a free Aircash virtual card in the app and you can start paying with it in just a few minutes.
 July 28, 2026Croatian highways in summer: a little trick that saves hours of waiting
 July 21, 2026Parking during summer in Croatia? A challenge almost every driver faces
 May 26, 2026Summer is too short to wait in front of toll booths
 May 26, 2026Why More and More People Are Paying Their Bills Through Aircash
 May 26, 2026The Worst Things That Can Happen While Traveling
 May 26, 2026Where to Go in Croatia for a Summer Vacation If You’re Not a Fan of the Sea
 May 26, 20265 Tips to Save Time and Money While Traveling
 May 18, 20265 Reasons the Aircash Mastercard should be your go-to card
 May 4, 2026Highway vignettes? There’s an app for that
 February 4, 2026How to Protect Children and Personal Data from Cyber Attacks?